 Nana Wu
A recent wave of scrutiny and criticism aimed at Environmental, Social, and Governance (ESG) investing, once perceived as a potential death knell for sustainable finance, has instead served as a powerful catalyst for its maturation. Far from ushering in a period of decline, the backlash has compelled a fundamental shift from aspirational claims to demonstrable evidence, forcing the industry to evolve and prove its worth through tangible outcomes.
For years, the discourse surrounding ESG and impact investing was characterized by a broad, albeit sometimes superficial, consensus. Funds touted their intentions, often framed by lofty goals and aspirational rhetoric. However, this era of "polite consensus" was ill-equipped to withstand the intense scrutiny that emerged over the past two years. This period of "bruising scrutiny" saw ESG funds experience significant outflows, leading many to believe that a reactionary winter had descended upon sustainable investing.
Yet, a closer examination of the industry’s trajectory suggests a different narrative. Rather than defeating the movement, the backlash has, paradoxically, propelled it forward. It has achieved what two decades of more gentle encouragement could not: compelling large asset managers to rigorously define and implement their fiduciary duties without the nebulous inclusion of E, S, or G in every conversation. The focus has irrevocably shifted from "we mean to do good" to the far more demanding question of whether anything was actually done.
The Shifting Landscape: From Intent to Evidence
Three years ago, the global investment landscape was already grappling with the sheer scale of capital dedicated to ESG and impact investing. At that time, the ESG sector had ballooned to an astonishing $30 trillion, with impact investing surpassing the $1 trillion mark. This growth occurred against the backdrop of a staggering global debt figure exceeding $307 trillion, highlighting the immense financial forces at play.
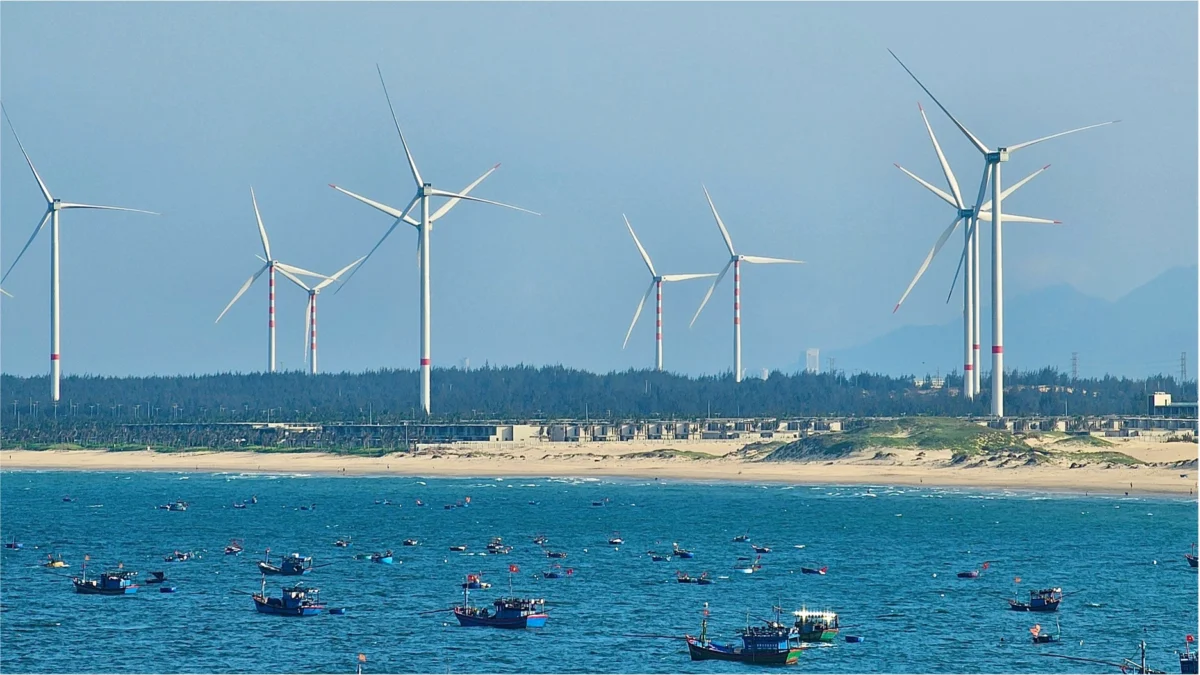
While headlines often focused on the perceived struggles of ESG, the underlying reality of the energy transition has been demonstrably unfolding. In 2025, for instance, renewable energy sources definitively overtook coal as the world’s leading source of electricity, with coal’s share of global generation falling below one-third. Investment in clean energy reached a record $2.2 trillion in that year, dwarfing the $1.1 trillion allocated to fossil fuels (oil, gas, and coal). By any objective measure, the energy transition is not merely a theoretical concept; it is a tangible and accelerating reality.
The recent backlash has acted as a powerful corrective, forcing a transition that can be likened to the difference between a man who claims to have crossed a room and one who is actually standing on the other side. This shift from intention to evidence is the most significant development in the sustainable finance arena.
Echoes from 2023: The "Tectonic Shift" and Its Prescient Warnings
In a 2023 primer titled "Tectonic Shift," the author’s team had already identified the burgeoning issue of greenwashing as the sector’s most damaging self-inflicted wound. The analysis sought to clarify critical distinctions: ESG as a process and a product, and impact investing as a more rigorous endeavor. At the time, there was cautious optimism regarding the harmonized definitions issued by prominent organizations such as the CFA Institute, the Global Sustainable Investment Alliance, and the Principles for Responsible Investment. The primer concluded with a call for the customary remedies: standardization, third-party verification, regulation, and education.
This approach was, by all accounts, sensible and professional, akin to the gradual reforms seen in the accounting sector. However, the reality that unfolded over the subsequent years proved to be far more dynamic and disruptive. The anticipated gradual cleanup did not materialize; instead, a more forceful reckoning ensued.
The Tripartite Assault: How the Backlash Unfolded (2024-2026)
The backlash against ESG and sustainable investing manifested on three interconnected fronts: political, regulatory, and market-driven.
Political Arena: ESG as a Campaign Trail Epithet
In the United States, "ESG" rapidly transformed into a potent campaign-trail epithet. The political climate became increasingly polarized, with "ESG" weaponized by those seeking to dismantle its influence. For example, the hypothetical "One Big Beautiful Bill Act" of 2025, while fictional in this context, illustrates the type of legislative actions that have been proposed or enacted to curb the growth and influence of sustainable investments. Such legislation, by accelerating the sunsetting of renewable energy tax credits, forced developers into a scramble to meet crucial deadlines, such as the July 4, 2026, cutoff for qualifying for older, more generous incentives. While the underlying projects might remain sound, this policy shift compelled them to justify their viability purely on economic merit, shedding reliance on policy tailwinds.
In parallel, regulatory bodies like the Securities and Exchange Commission (SEC) began to retreat from their oversight roles. By August 2026, the SEC had effectively ceased its role as an arbiter of which shareholder proposals companies could exclude, signaling a broader disengagement from actively guiding corporate sustainability practices.
Regulatory Overhaul: The European Experiment and its Revisions
Europe, long at the forefront of sustainable finance regulation, also experienced significant recalibration. The Sustainable Finance Disclosure Regulation (SFDR) was initially designed to certify funds as sustainable. However, it became apparent that meeting the stringent criteria for the top-tier "dark green" Article 9 designation – which requires sustainability to be the fund’s explicit investment objective – proved far more challenging than simply advertising compliance.
Consequently, a substantial number of Article 9 funds were downgraded to the less restrictive Article 8 designation. This trend culminated in November 2025, when the European Commission proposed a significant overhaul of the SFDR framework. The proposed replacement sought to simplify transparency rules by categorizing funds into three graded tiers. Crucially, each category would mandate that at least 70% of the portfolio demonstrably aligns with the fund’s stated objective. This shift fundamentally moved the goalposts from assertion to demonstrable alignment, a threshold that many funds failed to meet.
Market Realities: The Language Changes, the Commitment Endures
The market’s response, while not aligning with the most dire predictions of headlines, was nonetheless significant. According to the US SIF’s 2025 Trends Report, sustainable assets remained robust, holding steady at $6.6 trillion. However, the language used to describe these investments underwent a profound transformation.
When asked about the impact of the political backlash, a substantial 46% of firms reported no change in their approach. However, a significant 29% indicated a new emphasis on "demonstrable financial materiality," reflecting the view that ESG factors are relevant only when they directly influence financial returns. Furthermore, a notable 24% of firms had altogether dropped the term "ESG" from their lexicon.
Despite these shifts in terminology and focus, the underlying commitment to sustainable investing remained strong, with nearly 70% of managers affirming their long-term dedication to the principles. This suggests that managers were not abandoning their sustainable practices; they were simply reframing them and ceasing to label them as "ESG."
Evidence of Impact: Deals That Speak Louder Than Words
Amidst the regulatory and political turbulence, substantive deals continued to be executed, often with impressive commercial returns. In May 2026, KKR’s Global Impact fund, in partnership with XPV Water Partners, successfully sold the US water-quality business Axius Water to CRH for $700 million. This transaction is particularly noteworthy as it involved a strategic industrial buyer paying a full market price for an asset that was developed under an explicit impact thesis. The exit was achieved in what was described as the slowest private equity exit market in over a decade, underscoring the underlying value proposition of the business.
Just days prior, BTG Pactual’s Timberland Investment Group closed the largest reforestation fund on record, securing $1.24 billion for investments in Latin America. This achievement occurred in a market segment that the backlash narrative had largely written off as uninvestable. These deals, and others like them, demonstrate that impactful investments can and do generate commercial returns, even if they are no longer being marketed solely on their perceived virtue. The emphasis has shifted from how good the intentions were to how good the outcomes are.
The Crucial Shift: From Intentionality to Verifiable Accomplishment
For two decades, the impact investing field had largely organized itself around the question of intent. The primary criterion for admission into the "club" was whether a manager genuinely intended to achieve positive social and environmental outcomes, supported by a clear thesis, a roadmap aligned with Sustainable Development Goals, or a defined theory of change. Given that no fundraising deck would ever explicitly state an intention to cause harm, the answer was almost invariably "yes."
The past two years, while often graceless, have been profoundly effective in replacing that question with a far more rigorous one: not what the manager meant to do, but what the capital actually accomplished.
Impact investing, by its very nature, claims the same rigorous discipline as commercial investing: a clear thesis, concrete Key Performance Indicators (KPIs), verifiable measurement, and an unwavering willingness to adapt when data contradicts the initial pitch. The critical development is that the field is now being held to these stringent criteria. This newfound accountability has been facilitated by the standardization of definitions and the harmonization of reporting frameworks, allowing for genuine comparison between funds rather than mere admiration of their stated goals.
The era of relying solely on a manager’s goodwill has given way to a system of independent verification by third-party assessors. These assessors confirm the reality of a fund’s outcomes and validate that its methodology, KPIs, and on-the-ground evidence genuinely support its claims. Trust is now underpinned by demonstrable proof.
The Long Horizon of Financial Materiality and Societal Returns
The concept of financial materiality, particularly in the context of sustainable investments, operates over long horizons. The restoration of ecosystems, improvements in public health, advancements in education, and the alleviation of poverty are all processes that unfold over decades, not financial quarters. Society ultimately bears the cost of these challenges, whether through public budgets, lost productivity, or the compounding burden of social inequality.
Businesses that effectively address these systemic issues inherently create enterprises with material value. The successful exits of Axius Water and the significant capital raised for BTG Pactual’s reforestation fund serve as early, compelling evidence of this principle. These ventures demonstrate that addressing societal needs can be a powerful engine for commercial success.
Ultimately, returns matter. They always have, and they always will. The true test of impact capital was never solely about achieving immediate, risk-adjusted returns. It was, and remains, about whether the capital delivered on its stated objectives. The standards that the impact investing field always aspired to are now the standards by which it is being rigorously measured.
The Unfinished Task: Clearing the "Halo Merchants"
While the industry has made significant strides, a crucial challenge remains: the need to effectively identify and exclude what can be termed "halo merchants." These are traditional managers who have repackaged familiar investment strategies with a superficial "green tint," raising capital based on evocative imagery of those in need, and then exiting before any meaningful outcomes could be delivered. These are essentially "old wolves with better tailors." The real diligence now lies in distinguishing between genuine impact and mere window dressing. This requires a discerning eye and a commitment to verifying substance over style, ensuring that the hard-won rigor of the past few years is not undermined by those seeking to exploit the renewed focus on sustainable value creation.

 Nana Muazin